SEBON
Investor Coalitions Press SEBON for Sweeping Market Reforms: Demand T+1 Settlement, 30% Minimum Public Float
Finally, the associations have called for stringent, uniform regulatory guidelines regarding margin trading across all brokerage firms. Currently, fragmented practices regarding interest rates and risk management expose the market to systemic vulnerabilities. The investors recommend implementing risk-based margin rates, where highly volatile or risky stocks require tighter credit controls. To achieve these sweeping reforms, the coalitions have urged SEBON to abandon unnecessary bureaucratic hurdles and immediately initiate cross-institutional dialogues involving the central bank, NEPSE, CDSC, brokers, and listed companies to foster a secure and fair trading environment.
Dipesh Ghimire
3 min read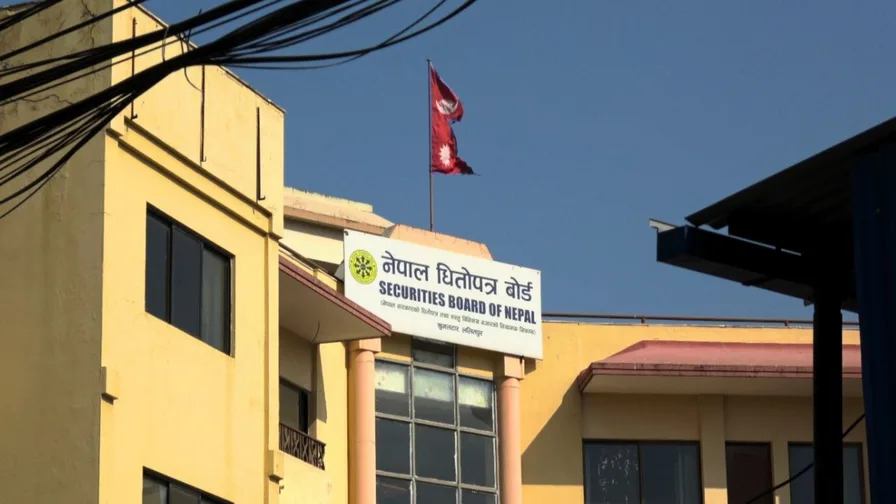
KATHMANDU — In a concerted push to modernize Nepal’s stock market and dismantle ongoing regulatory bottlenecks, three prominent investor associations have submitted a comprehensive six-point policy reform proposal to the Securities Board of Nepal (SEBON). Seeking to transform the domestic bourse into a more transparent, efficient, and investor-friendly platform, the umbrella bodies are advocating for structural changes—ranging from expediting trade settlements to ensuring a larger chunk of corporate equity is floated to the general public.
The joint memorandum, submitted on Tuesday by the Nepal Investor Forum, Nepal Capital Market Investors Association, and Share Investors Association Nepal, highlights systemic flaws that have historically stifled market liquidity and investor confidence. Signed by association leaders Tulsiram Dhakal, SP Chaulagai, and Tara Prasad Fullel, the document serves as a stark reminder to the regulatory authority that the capital market must evolve from a mere speculative trading hub into a robust engine for national capital formation, industrial expansion, and economic prosperity.
A primary grievance raised by the investor coalitions is the highly restrictive provision requiring a 15-day prior notice for selling shares. The associations argue that this rule fundamentally contradicts the core principles of a free market. While investors can buy shares instantly, forcing them to declare their intent to sell a fortnight in advance artificially chokes market supply, traps liquidity, and infringes upon retail investors' rights to independent trading. To rectify this, the groups have demanded the complete scrapping of this rule for general investors. However, to maintain corporate transparency, they proposed a revised 7-day prior notice specifically for institutional and strategic promoters attempting to offload massive holdings (over 5 percent). The memorandum logically suggests routing such massive liquidations through an "Offer for Sale" or specialized block trading mechanism to prevent erratic price manipulations in regular trading hours.
Addressing the persistent supply-demand imbalance in the secondary market, the proposal strongly advocates for a mandatory minimum 30 percent public share issuance (IPO) threshold for all companies going public. Historically, companies floating meager percentages of their equity have created an artificial scarcity of shares, driving unnatural and highly volatile price speculation. The investors argue that, following a proper assessment of a company's capital and risk profile, the regulatory framework should even explore pushing the public float up to 50 percent for highly suitable companies. Financial observers note that this move would democratize corporate ownership, dilute the disproportionate market dominance of promoter shares, and allow stock prices to be determined by genuine market fundamentals.
The joint appeal also sheds light on severe administrative and technical disjoints between the Nepal Stock Exchange (NEPSE) and CDS and Clearing Limited (CDSC), particularly concerning the cost calculation of bonus and right shares. Because of differing metrics in adjusted base prices between the two entities post-book closure, retail investors are frequently penalized with Capital Gains Tax (CGT) even when they haven't booked actual portfolio profits. The organizations have demanded an integrated, scientific calculation method to ensure taxes are levied only on actual capital gains.
Furthermore, highlighting the financial risks posed by delayed share transfers—especially during sharp market downturns where investors are trapped unable to sell—the coalitions have urged SEBON to immediately initiate feasibility studies to scrap the current T+2 or T+3 settlement cycles. Transitioning to a T+1 (Trade plus one day) or faster automated settlement system, they argue, would drastically enhance market liquidity, minimize price exposure risks, and boost overall investor trust.
Finally, the associations have called for stringent, uniform regulatory guidelines regarding margin trading across all brokerage firms. Currently, fragmented practices regarding interest rates and risk management expose the market to systemic vulnerabilities. The investors recommend implementing risk-based margin rates, where highly volatile or risky stocks require tighter credit controls. To achieve these sweeping reforms, the coalitions have urged SEBON to abandon unnecessary bureaucratic hurdles and immediately initiate cross-institutional dialogues involving the central bank, NEPSE, CDSC, brokers, and listed companies to foster a secure and fair trading environment.
Advertisement
Written by
Dipesh Ghimire