Top2 min readSectoral Rotation in NEPSE Bull Markets and What It Suggests About the Current Bull RunSectoral Rotation in NEPSE Bull Markets and What It Suggests About the Current Bull Run Nepal's stock market (NEPSE) has historically shown cyclical behavior, with every bull run carrying distinct sectoral characteristics. Using past data patterns, we can break down the key trends and derive insights into how the current market momentum might unfold.Dipesh Ghimire·9 Jul, 2025
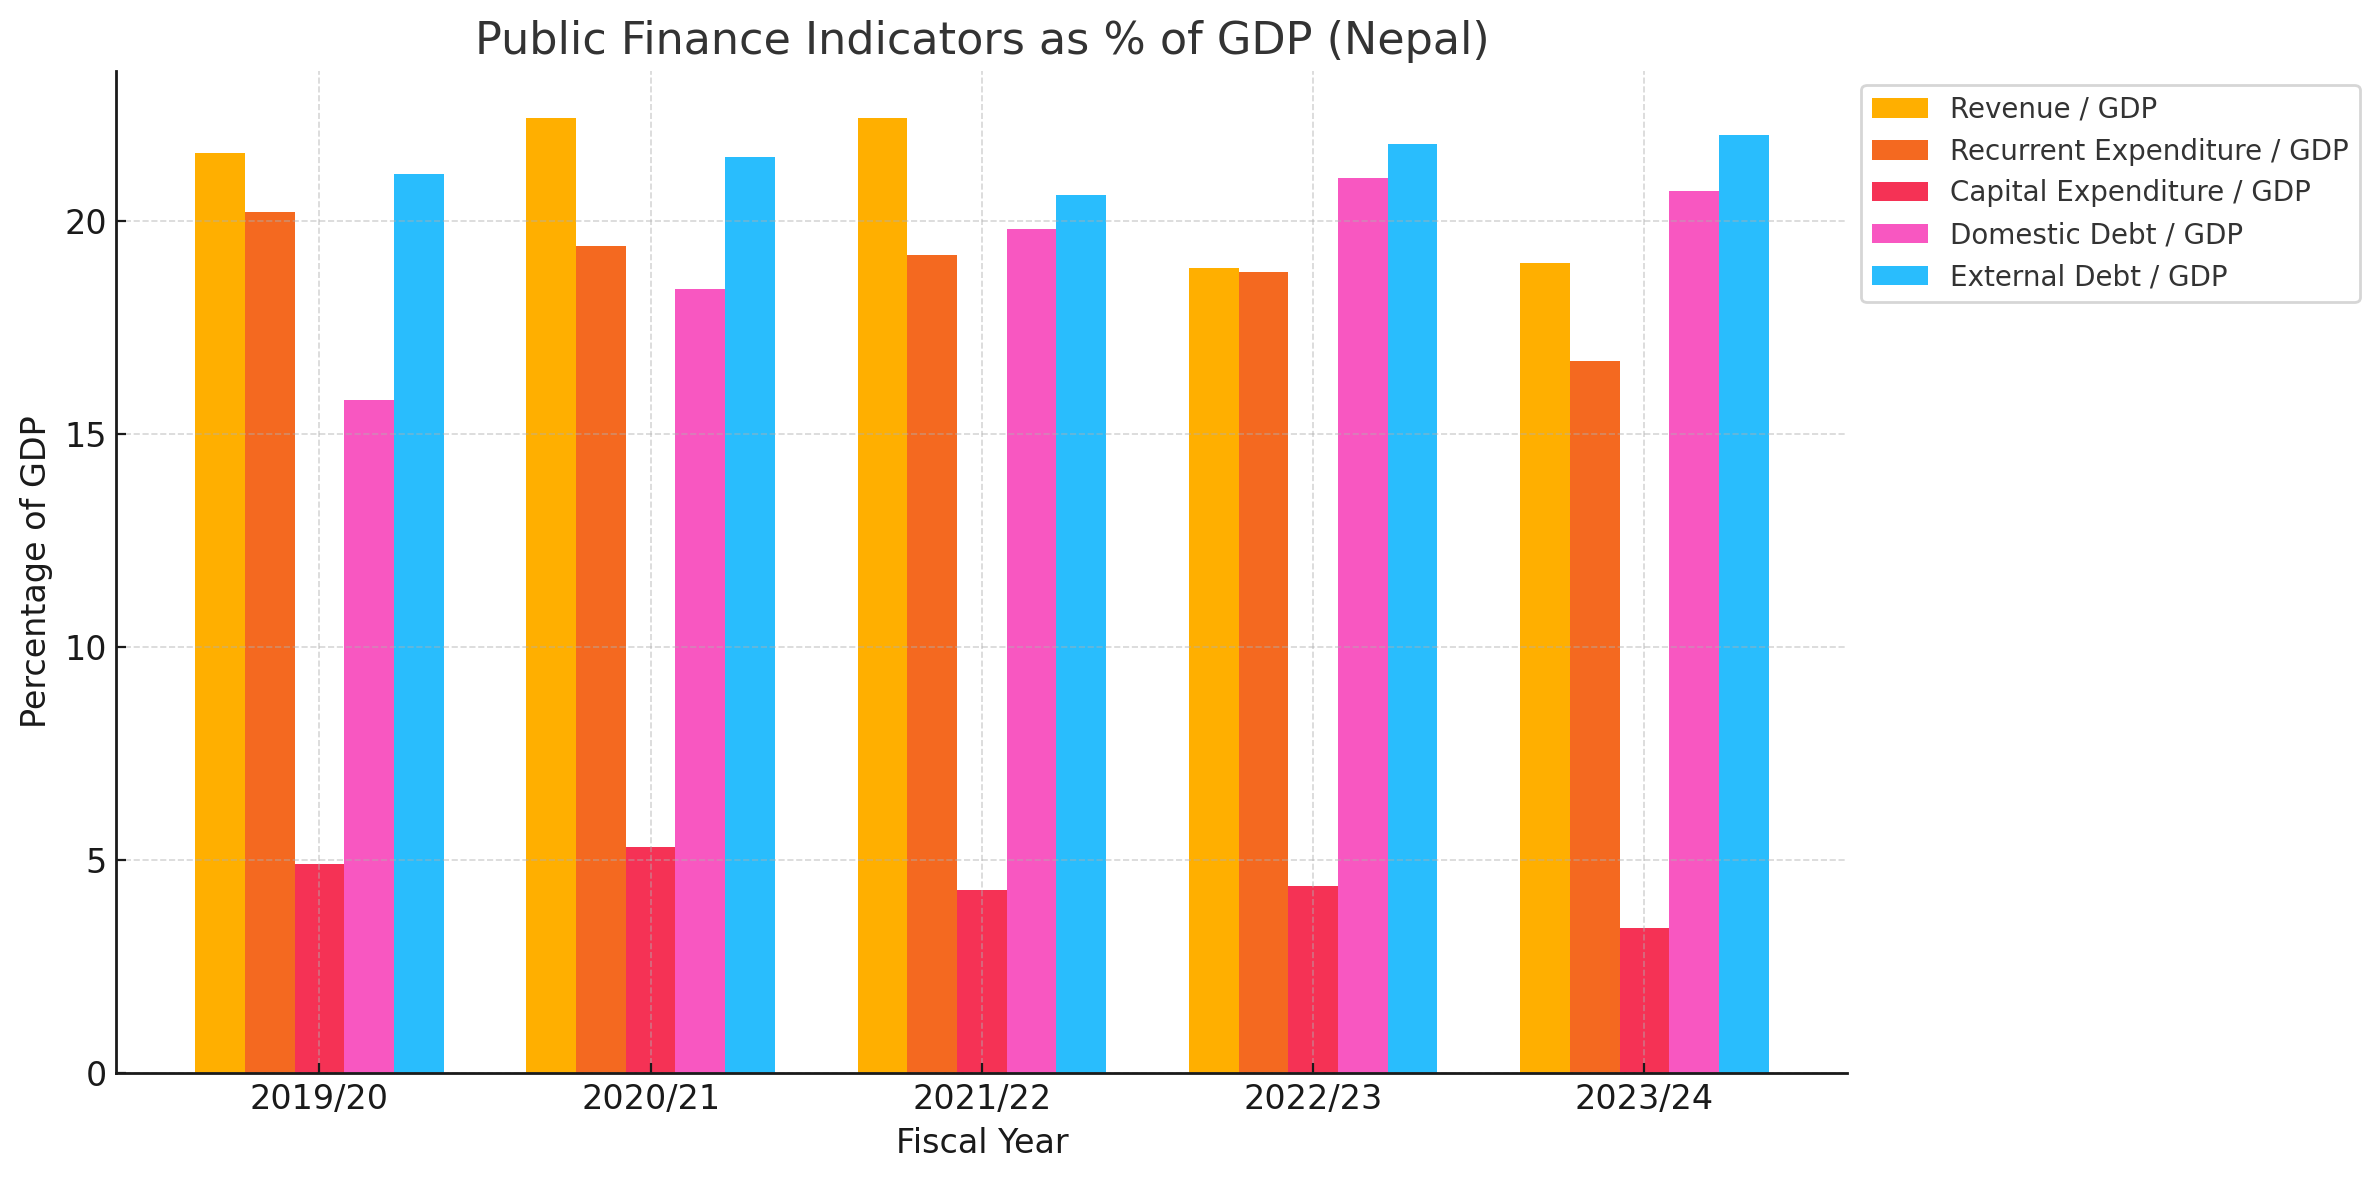
GDP2 min readPublic Finance Indicators Reflect Mixed Fiscal Trends in NepalThe summary of Nepal's public finance indicators reveals notable fiscal shifts over the past five years. The Revenue to GDP ratio declined from a high of 22.4% to 19.0%, indicating reduced government income generation relative to economic output. Similarly, Recurrent Expenditure to GDP decreased from 20.2% to 16.7%, reflecting either improved spending efficiency or restrained budgetary allocations. However, Capital Expenditure to GDP also declined sharply from 5.3% to 3.4%, suggesting a slowdown in developmental and infrastructure investments. On the debt side, Domestic Debt to GDP rose from 15.8% to a peak of 21.0%, settling slightly lower at 20.7%, while External Debt to GDP climbed consistently, reaching 22.0%. Overall, the data highlights increasing reliance on debt financing and declining investment in capital formation, raising concerns about fiscal sustainability and long-term economic growth.Sandeep Chaudhary·8 Jul, 2025
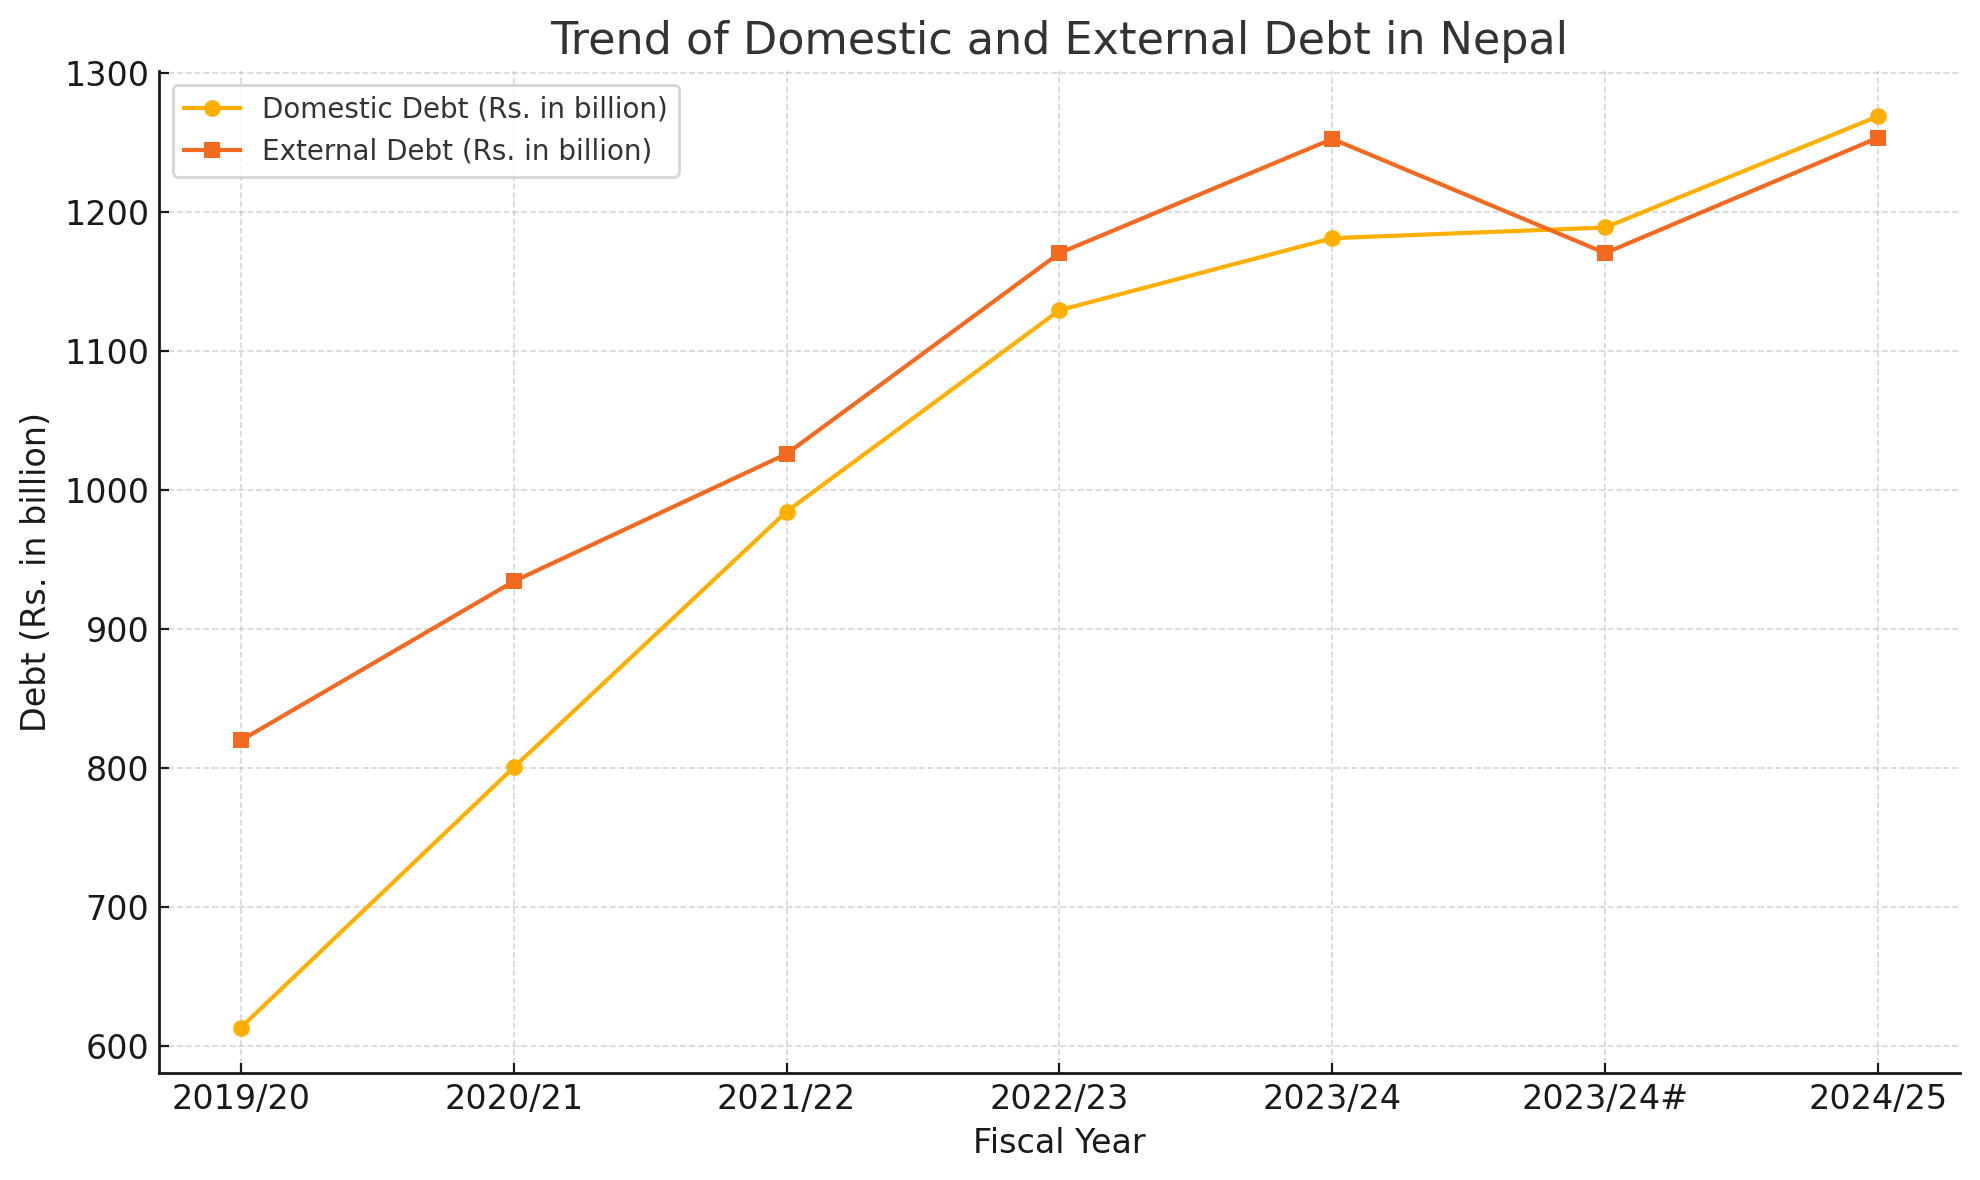
Public finance1 min readPublic Debt Dynamics in Nepal: Domestic and External Liabilities Continue to RiseNepal’s public debt has steadily increased over the past six fiscal years, with both domestic and external borrowings rising significantly. Domestic debt rose from Rs. 613.2 billion in 2019/20 to Rs. 1268.6 billion in 2024/25, showing a consistent upward trend. Similarly, external debt climbed from Rs. 819.7 billion to Rs. 1253.2 billion over the same period, though it dipped slightly in mid-2023/24 before rebounding. This growth highlights the government’s reliance on debt financing to support development projects and budgetary needs. The data signals a growing fiscal burden and the need for strategic debt management to ensure long-term sustainability.Sandeep Chaudhary·8 Jul, 2025
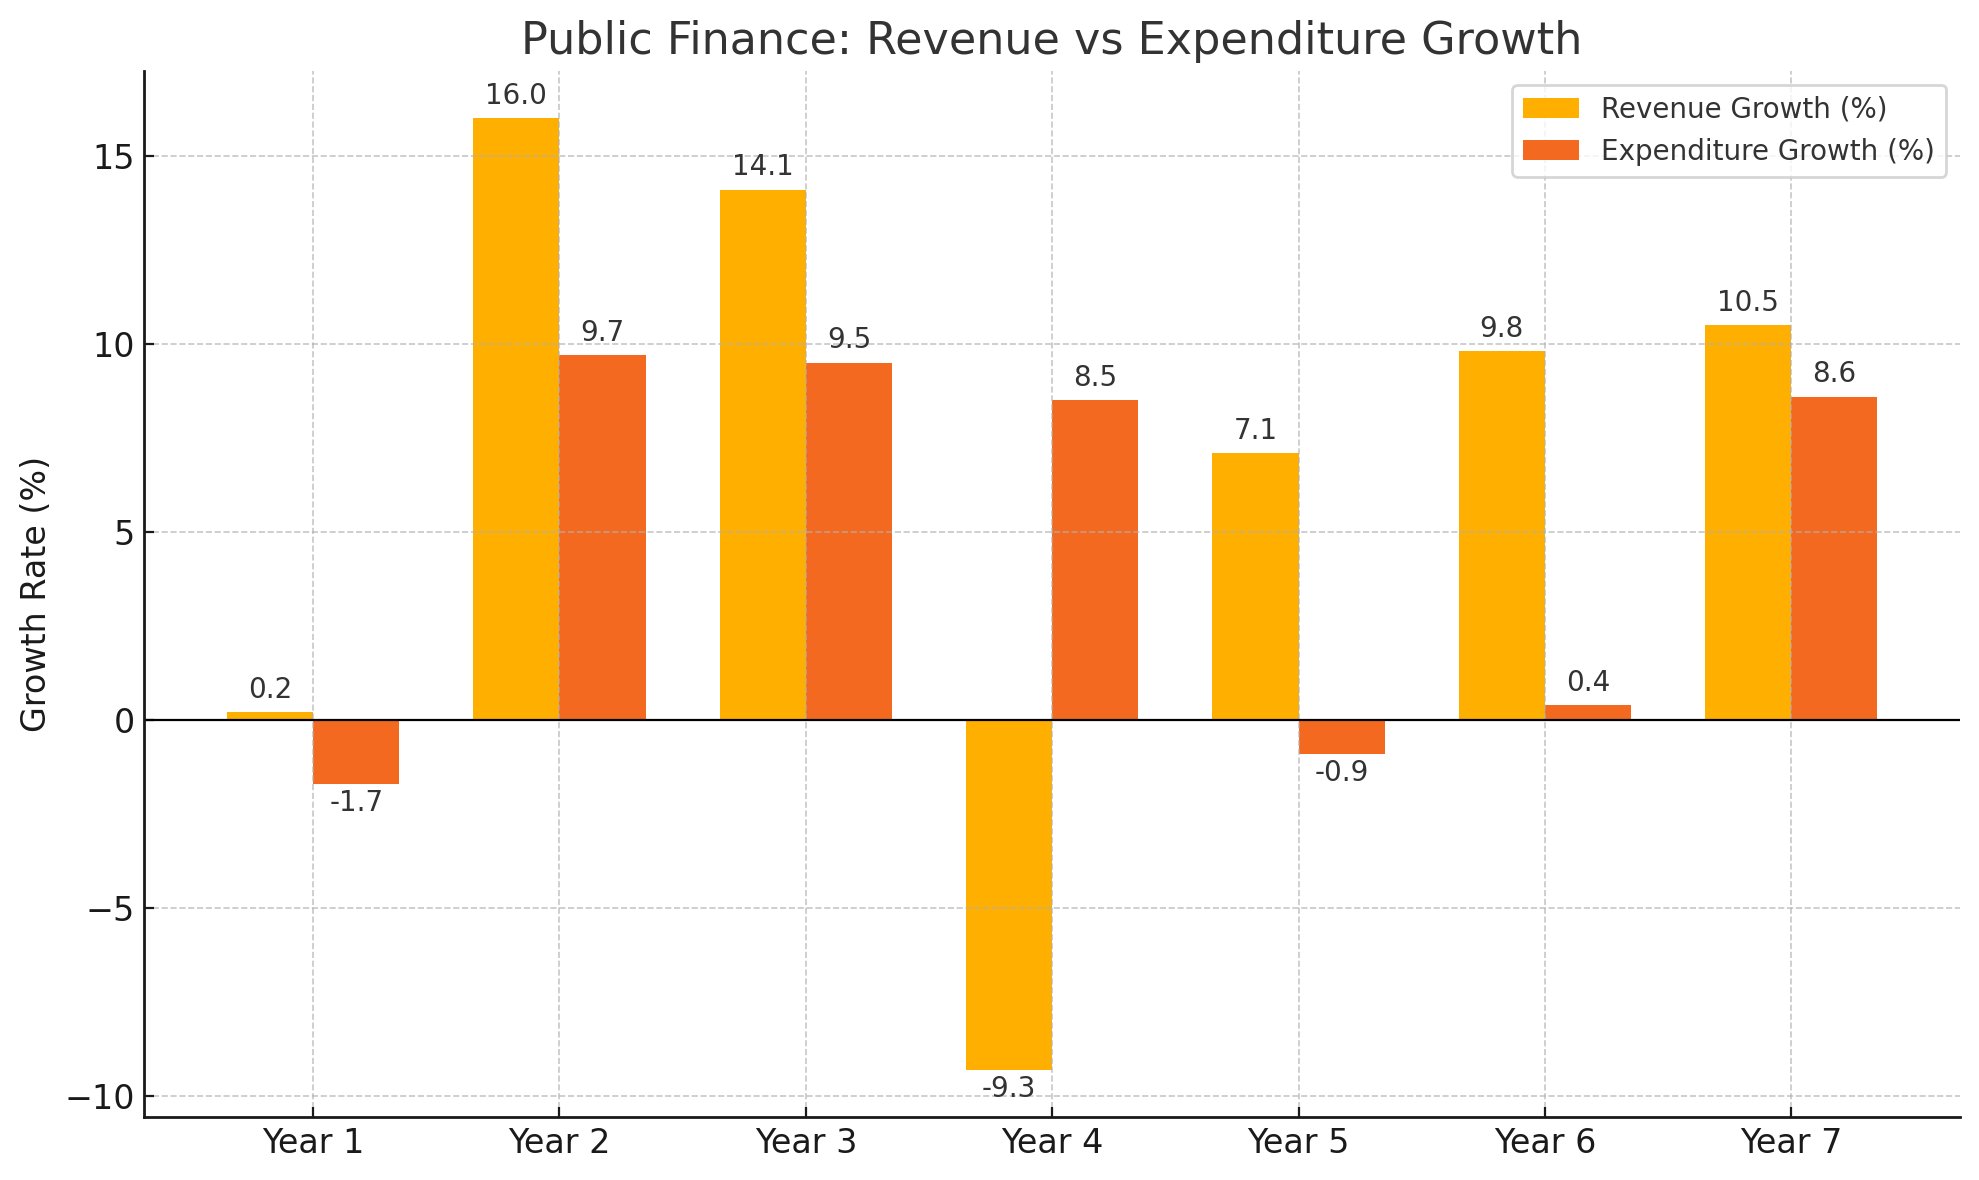
public finance1 min readPublic Finance Trends Show Fiscal Recovery with Moderate Revenue GrowthThe summary of Nepal's public finance data reveals a gradually improving fiscal environment. Revenue growth, after facing a sharp decline of -9.3% in one fiscal year, has steadily rebounded to 7.1%, then 9.8%, and most recently 10.5%. This upward trend suggests strengthened tax collection and economic recovery. On the expenditure side, growth remained controlled, fluctuating between minor contractions and moderate increases, ending with an 8.6% rise. The gap between revenue and expenditure growth has narrowed in recent years, indicating more balanced fiscal management and reduced budgetary stress. Overall, the government appears to be maintaining cautious spending while steadily boosting revenuesSandeep Chaudhary·8 Jul, 2025
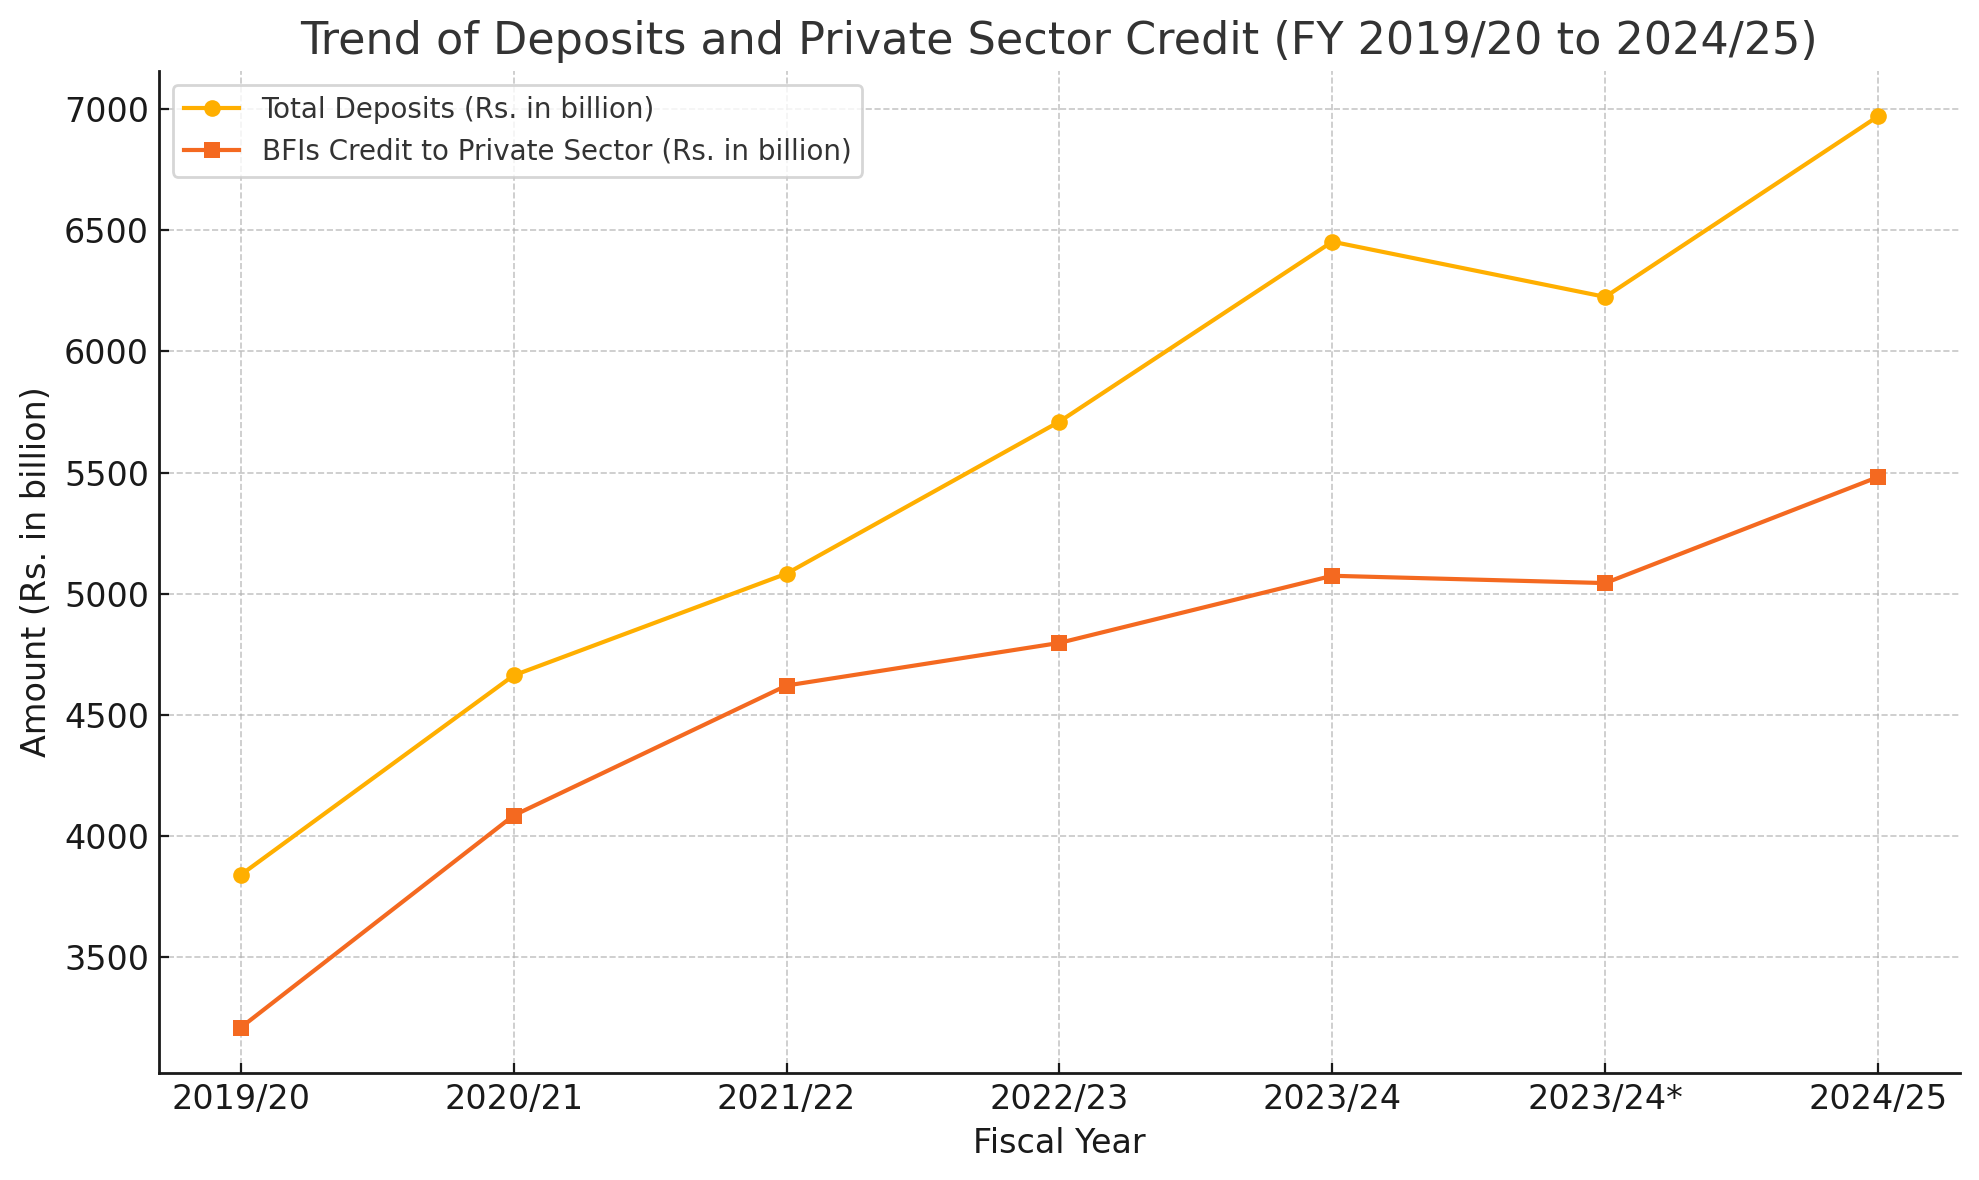
deposit1 min readDeposits and Private Sector Credit Continue to Rise in Nepal’s Banking SectorFrom FY 2019/20 to FY 2024/25, Nepal’s banking sector has shown strong momentum in deposit mobilization and private sector credit expansion. Total deposits rose significantly from Rs. 3,839.7 billion to Rs. 6,970.0 billion, reflecting a steady increase in public savings and trust in formal banking. Likewise, credit disbursed by BFIs to the private sector grew from Rs. 3,209.8 billion to Rs. 5,481.6 billion. While both indicators showed a slight contraction in FY 2023/24*, they rebounded sharply in FY 2024/25, indicating renewed financial activity. The growing gap between deposits and credit suggests increasing liquidity in the banking system, emphasizing the need for strategic credit deployment to stimulate economic growth.Sandeep Chaudhary·8 Jul, 2025
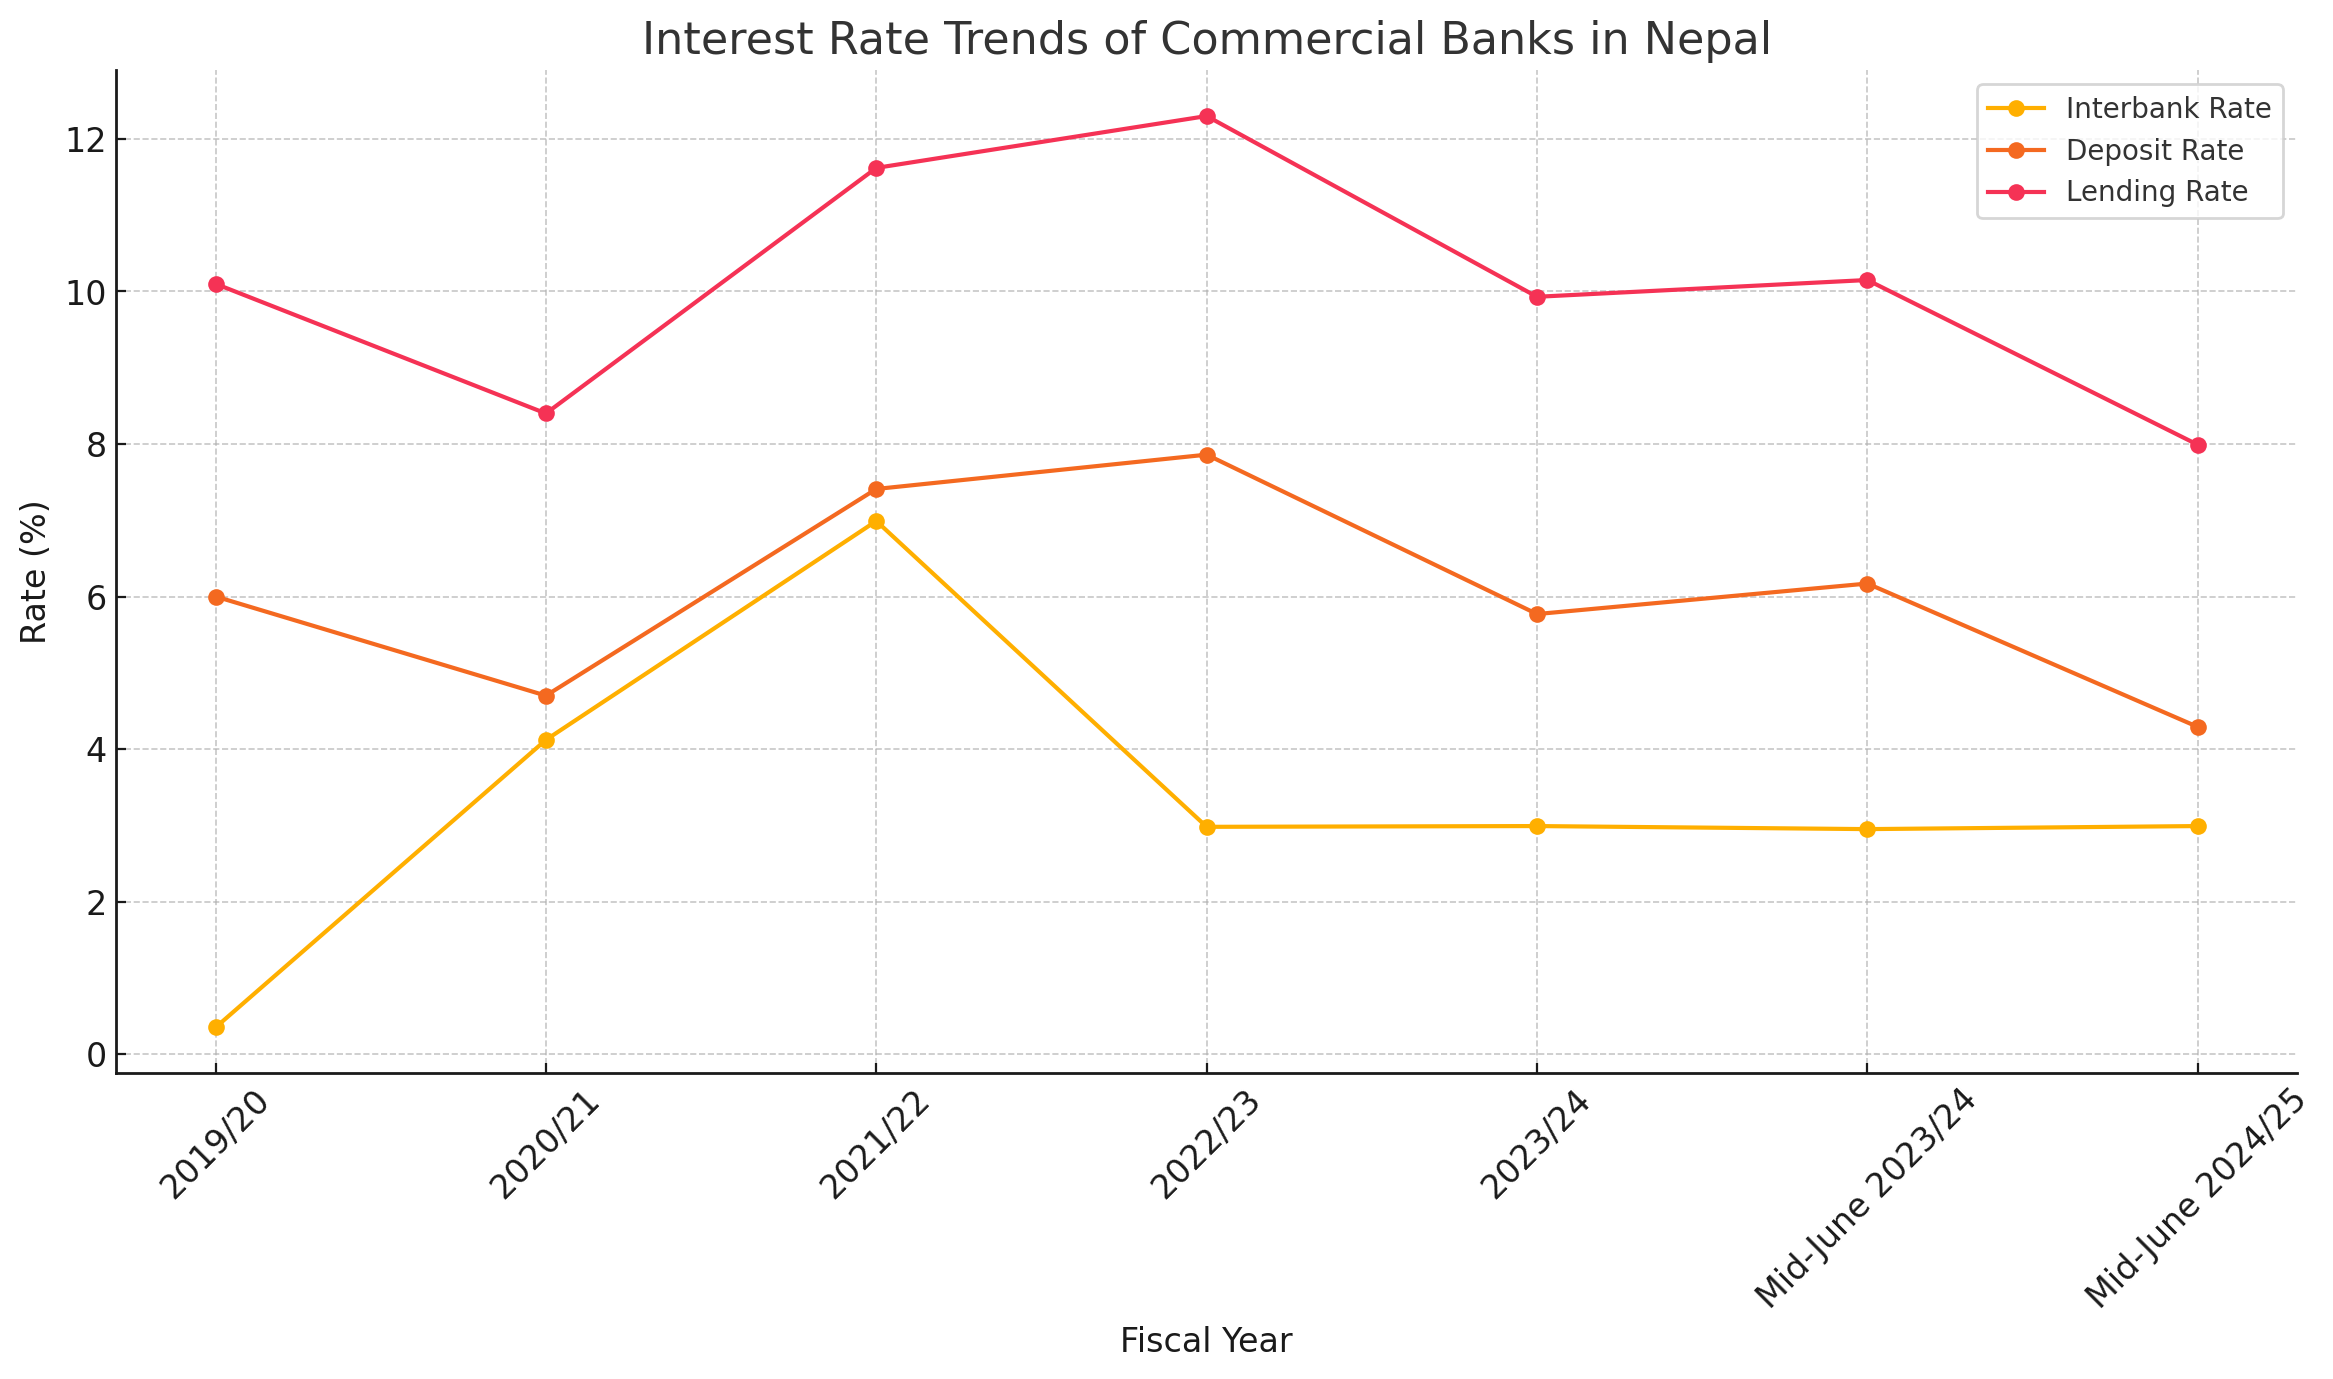
WAIR1 min readCommercial Bank Interest Rate Trends Indicate Declining Cost of Credit in NepalAs of mid-June 2024/25, Nepal’s commercial banking sector has experienced a notable decline in key interest rates, signaling improved liquidity and a softening in monetary conditions. The weighted average interbank rate remained stable at 2.99%, reflecting ease in short-term interbank borrowing. Meanwhile, the deposit rate fell significantly to 4.29% from 6.17% a year earlier, indicating reduced competition among banks for public deposits. Most notably, the lending rate dropped sharply to 7.99% from 10.15%, making credit more affordable for borrowers. This downward trend in interest rates across all categories suggests that commercial banks are operating under a more accommodative environment, likely in response to policy shifts aimed at stimulating economic growth.Sandeep Chaudhary·8 Jul, 2025
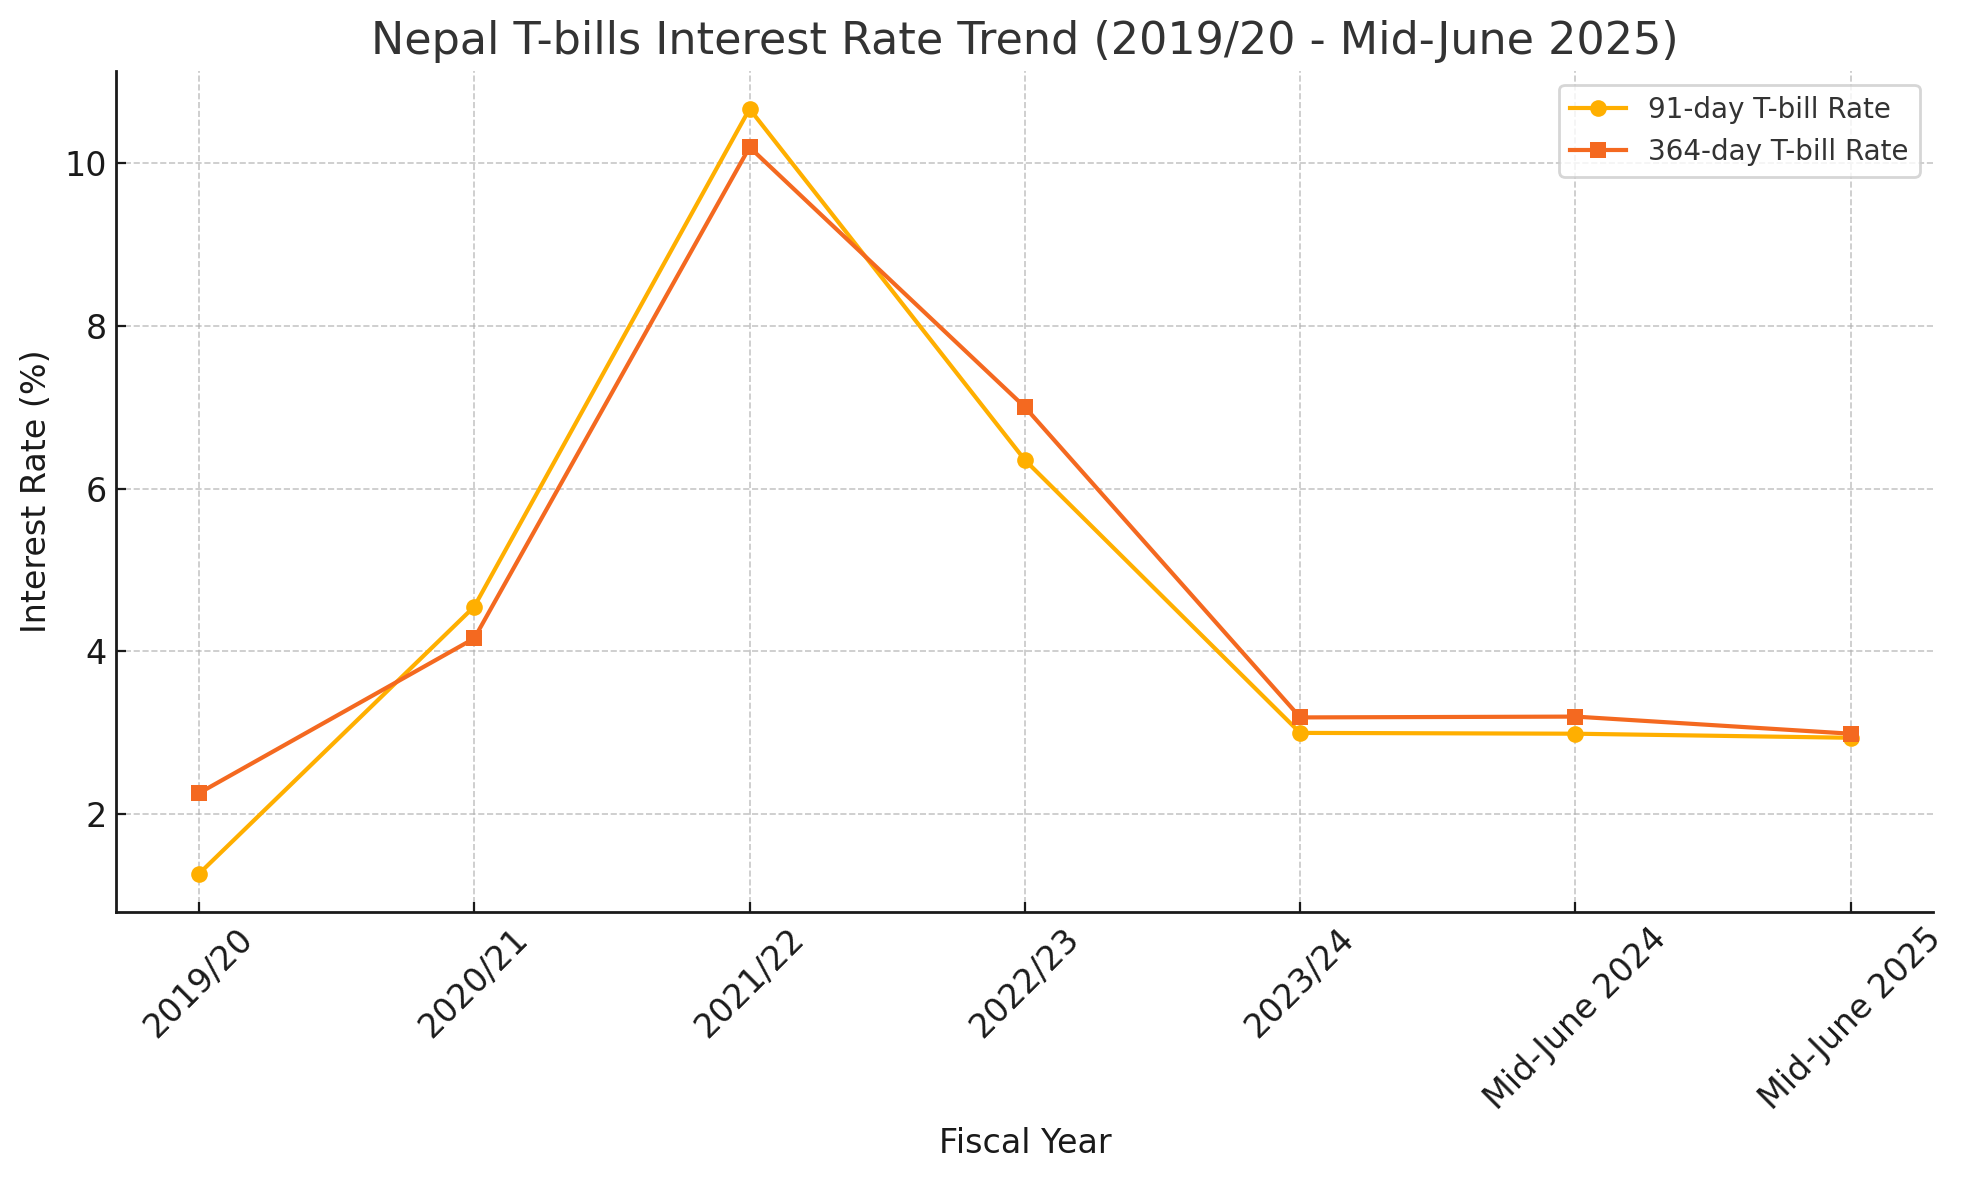
Tbills1 min readNepal T-Bill Rates Reflect Eased Liquidity Pressure in FY 2024/25The interest rates of Nepal’s Treasury bills have shown a clear declining trend after peaking in FY 2021/22, indicating improved liquidity conditions and a more accommodative monetary policy. The 91-day T-bill rate, which had surged to 10.66% in 2021/22, dropped sharply to 6.35% in 2022/23 and further declined to 2.94% by mid-June 2025. Similarly, the 364-day T-bill rate fell from 10.19% in 2021/22 to 7.00% in 2022/23, then continued decreasing to 2.99% by mid-June 2025. This softening of short-term government security yields suggests reduced credit stress in the banking sector and signals stable inflation expectations and a surplus liquidity environment in the financial system.Sandeep Chaudhary·8 Jul, 2025
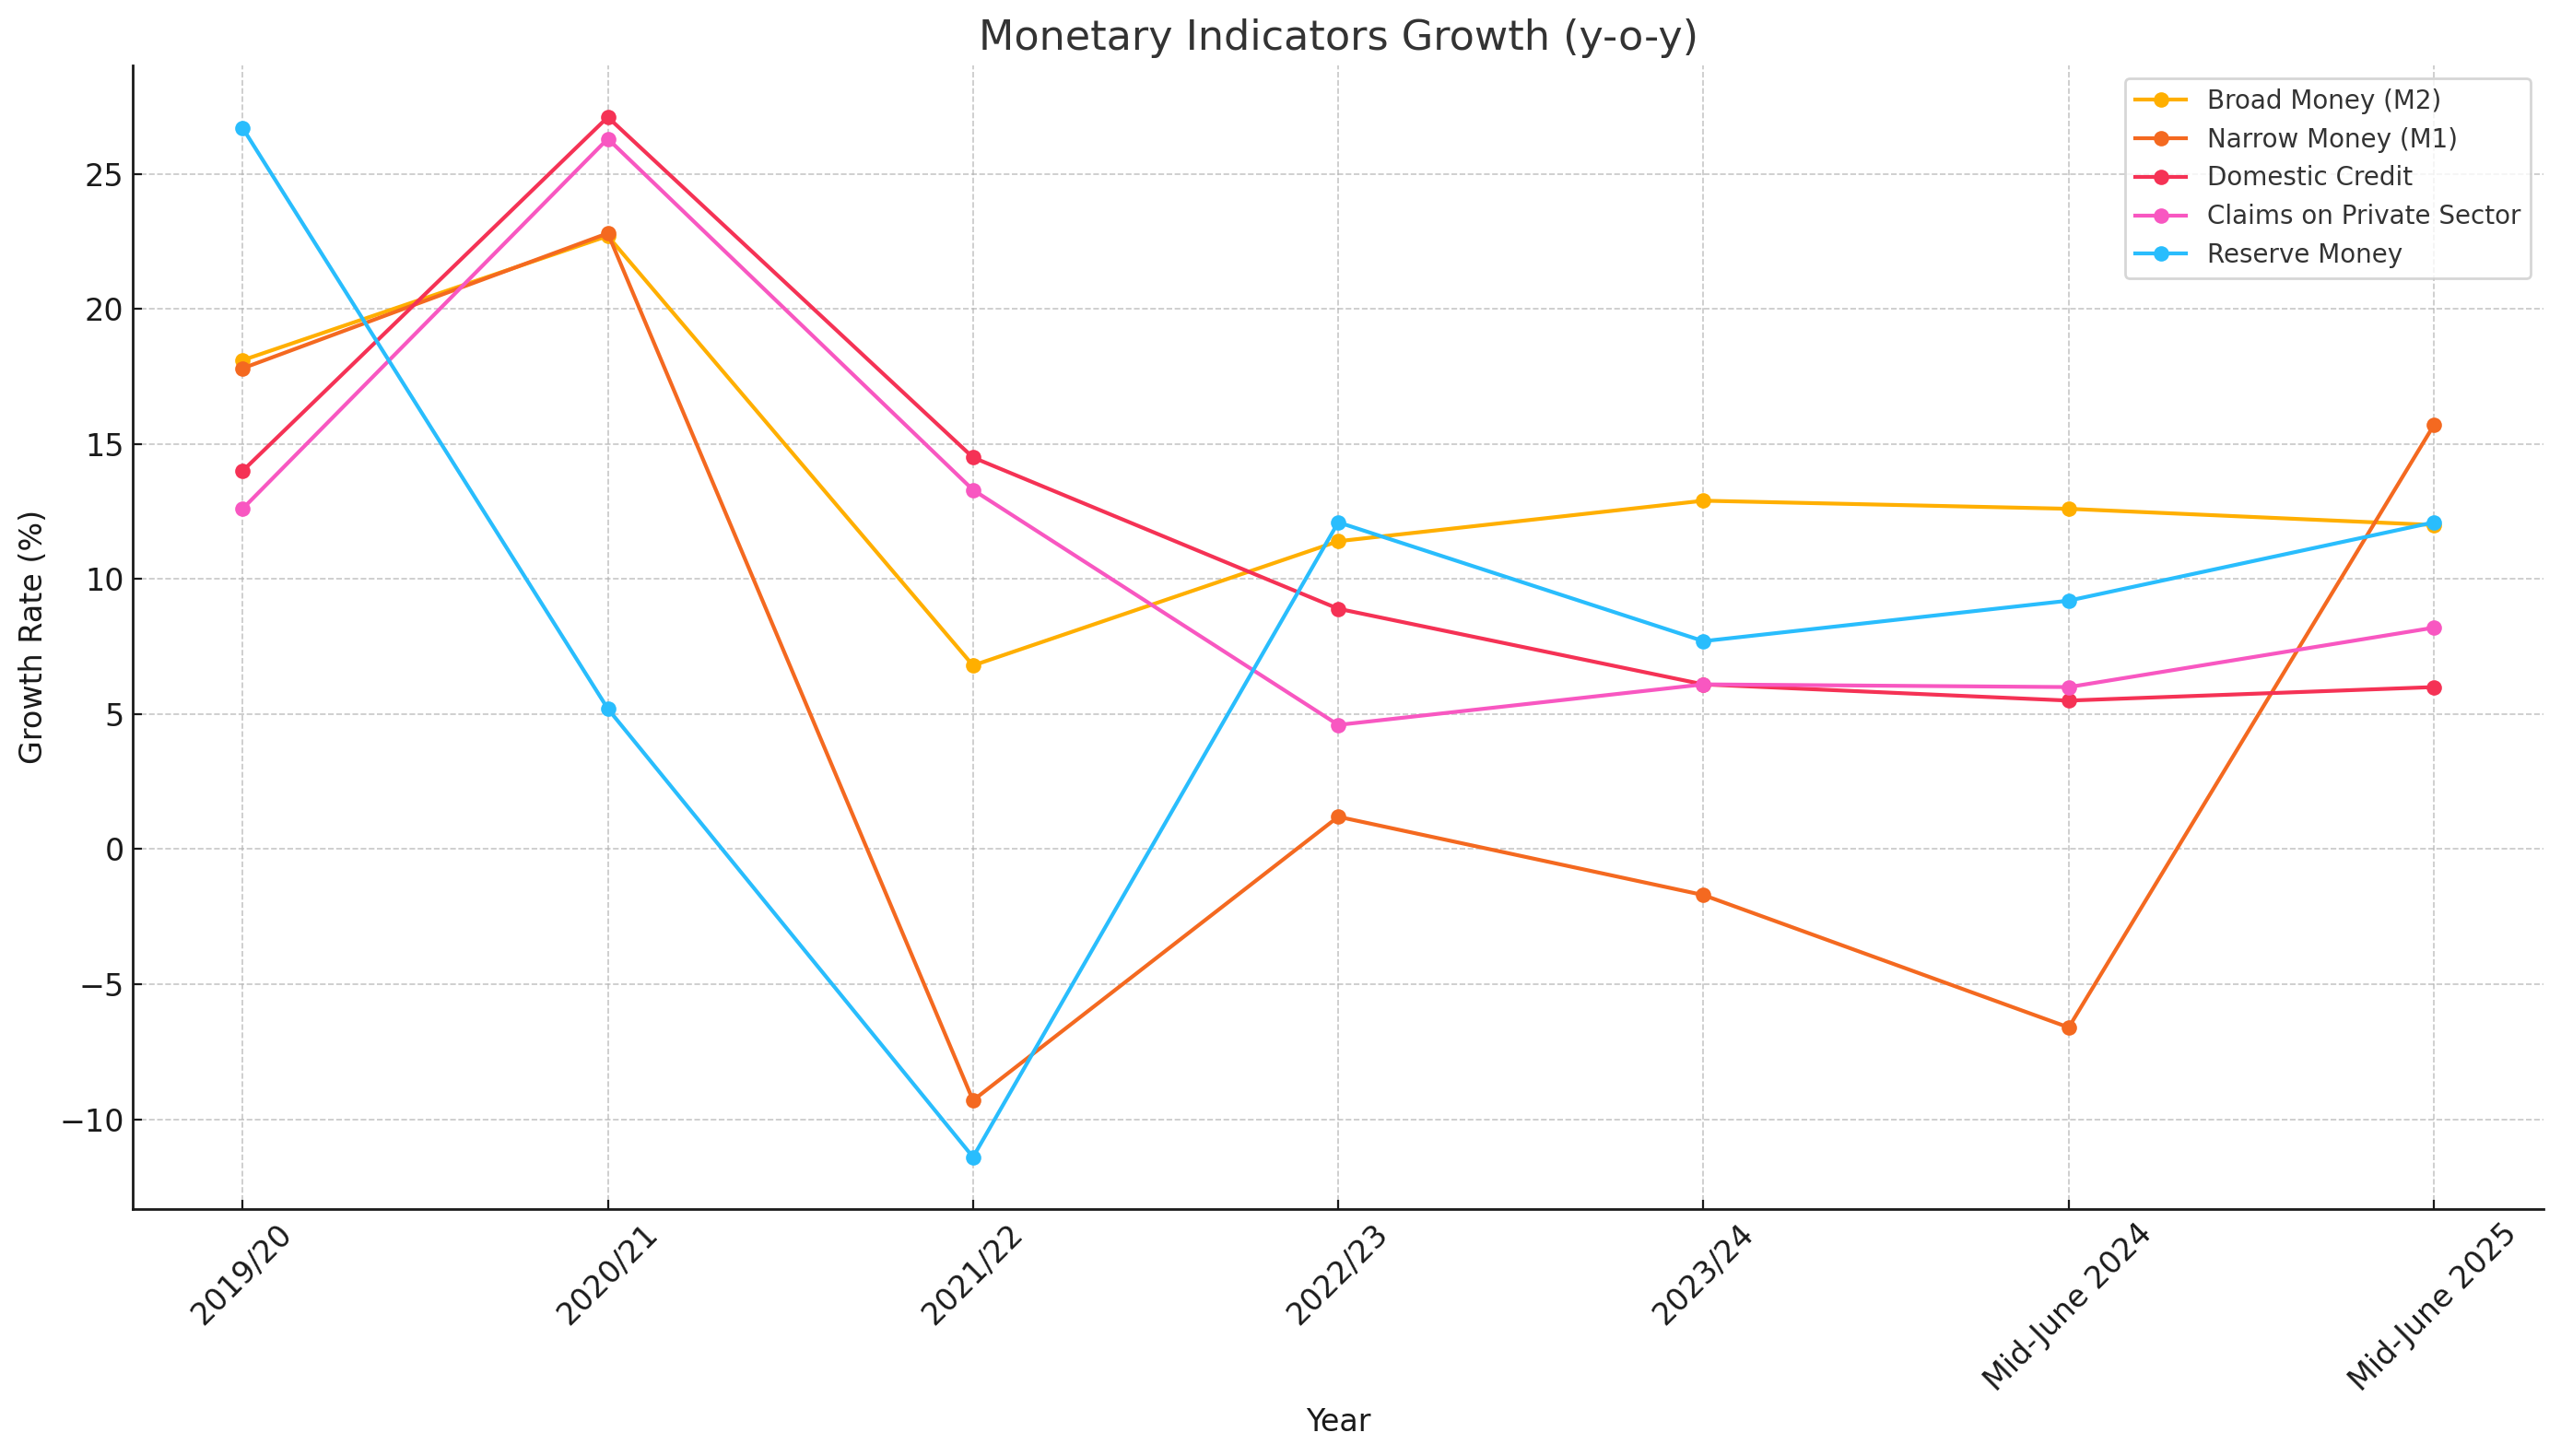
M22 min readMonetary Indicators Reflect Gradual Stabilization in Nepal's EconomyAs of mid-June 2025, Nepal’s key monetary indicators reflect gradual recovery and stabilization. Broad Money (M2) maintained consistent growth at 12%, showing stable liquidity in the economy. Narrow Money (M1) sharply rebounded to 15.7% after negative growth in the past two years, signaling improved public confidence and higher cash circulation. Domestic Credit growth remained modest at 6%, indicating cautious lending behavior, while Claims on the Private Sector improved to 8.2%, suggesting a slight pickup in private borrowing. Reserve Money growth rose to 12.1%, showing the central bank's efforts to ensure adequate base money to support monetary expansion. Overall, the data points toward a recovering monetary environment with renewed momentum in money supply and credit flow.Sandeep Chaudhary·8 Jul, 2025
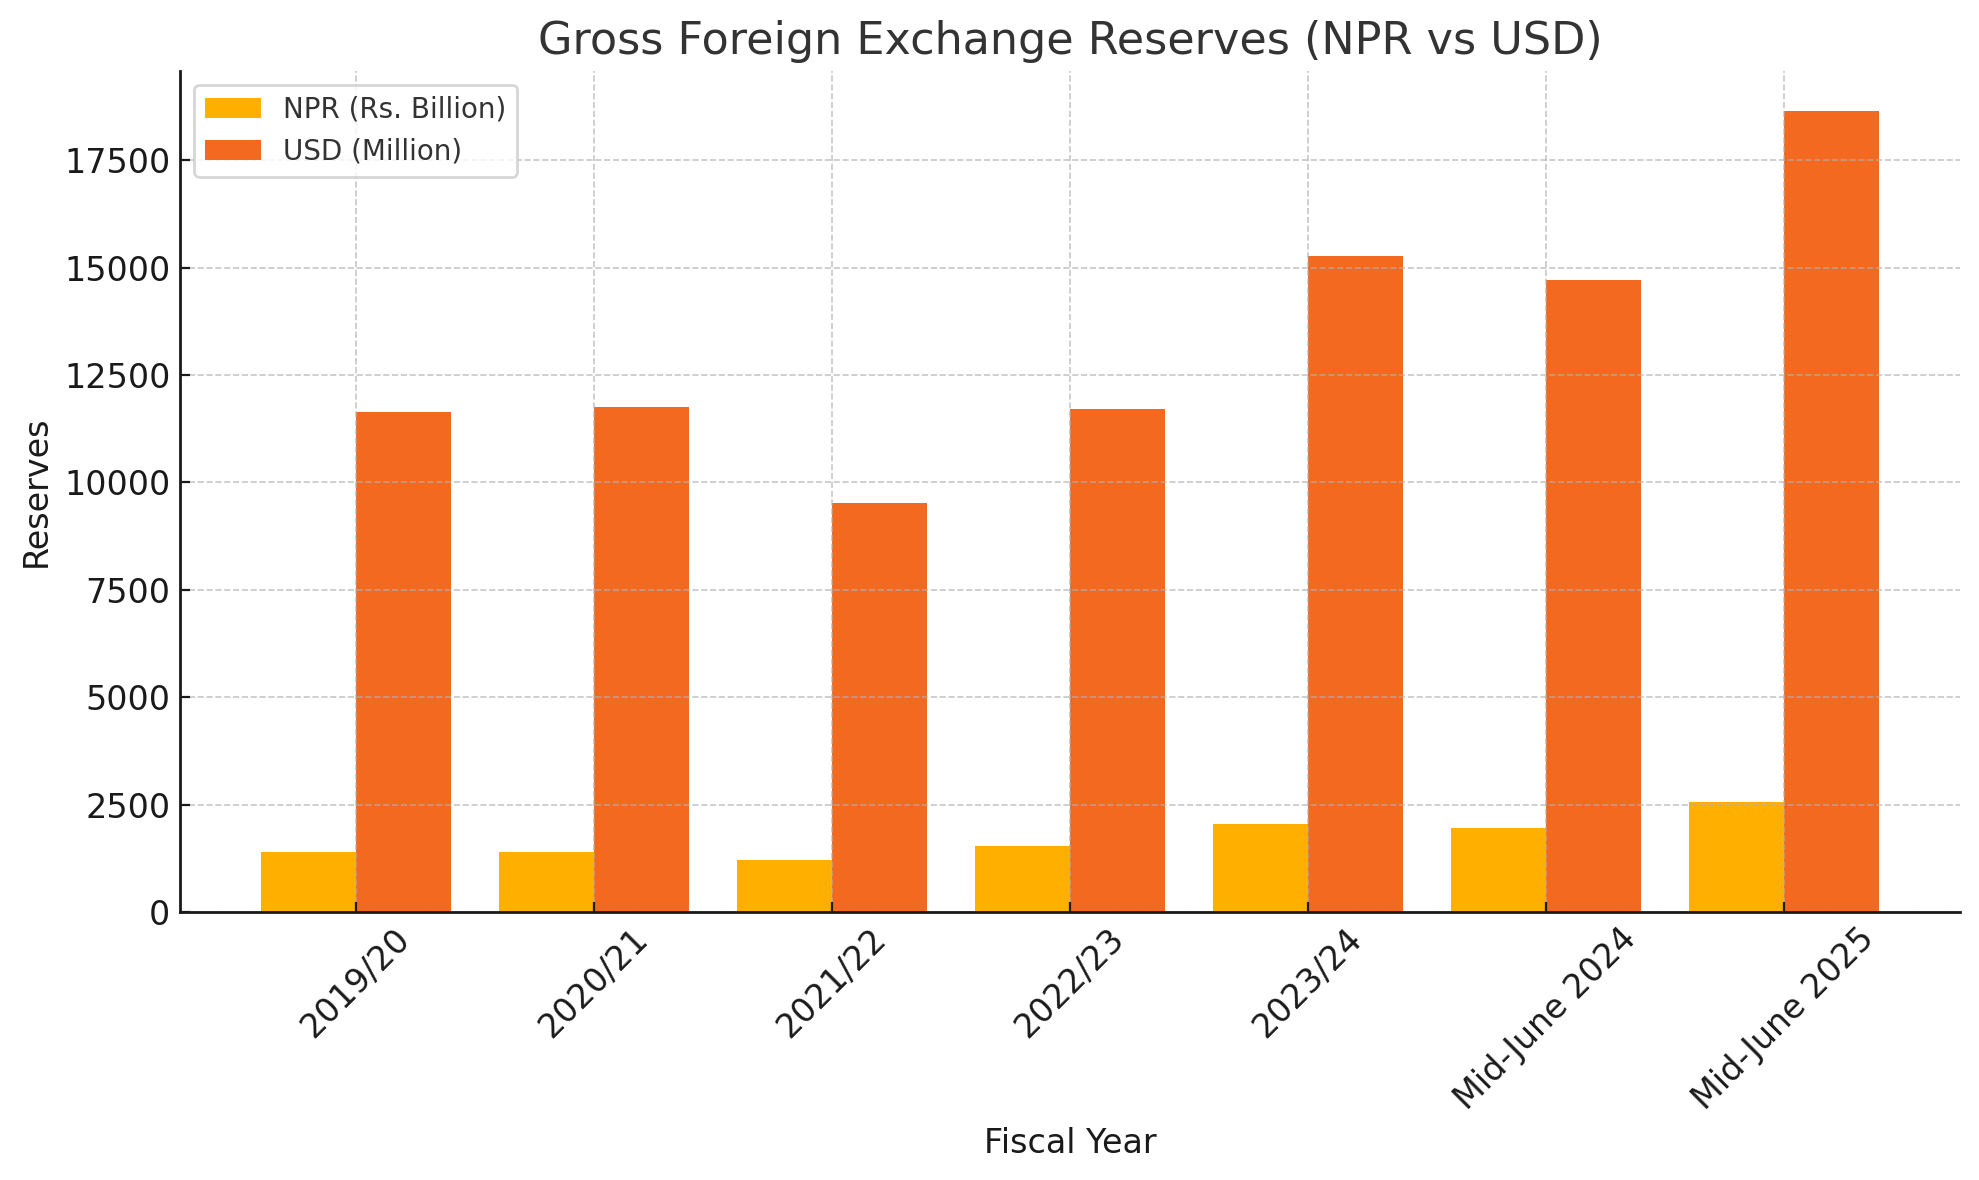
USD1 min readNepal’s Foreign Exchange Reserves Surge to Historic High in FY 2024/25As of mid-June 2025, Nepal’s gross foreign exchange reserves have witnessed a remarkable surge, reaching Rs. 2,569.4 billion (approx. USD 18.65 billion). This marks a substantial improvement from mid-June 2024, when reserves stood at Rs. 1,967.2 billion (USD 14.72 billion). The upward trend reflects consistent recovery and external sector strengthening, supported by increased remittance inflows, narrowing trade deficits, and improved current account performance.Sandeep Chaudhary·8 Jul, 2025
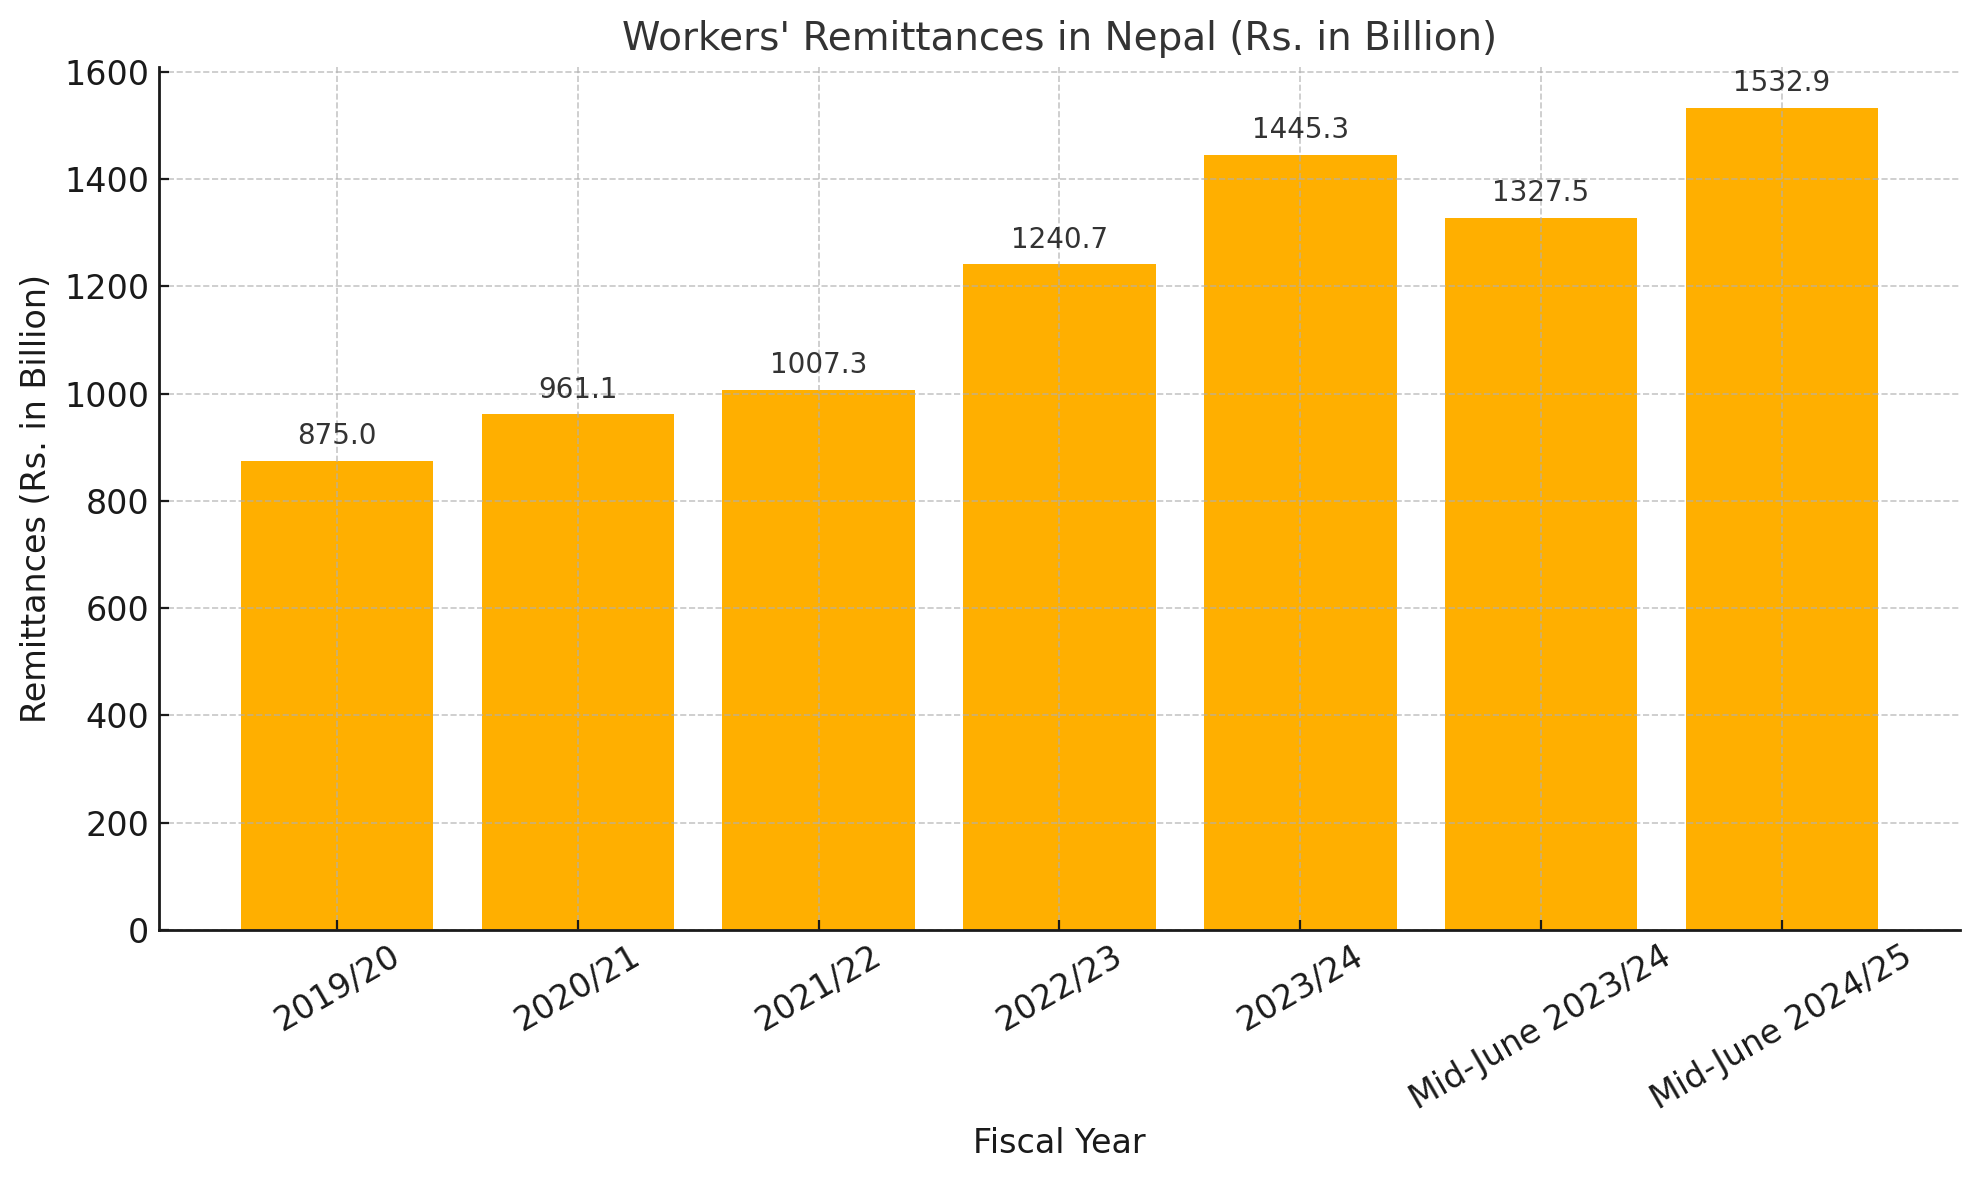
Remittance1 min readSteady Rise in Remittance Bolsters Nepal's Foreign EarningsNepal's workers' remittances have shown a consistent upward trend over the past six years, playing a crucial role in supporting the country’s economy. Starting at Rs. 875 billion in 2019/20, remittances rose steadily each year—reaching Rs. 961.1 billion in 2020/21, Rs. 1,007.3 billion in 2021/22, and Rs. 1,240.7 billion in 2022/23. A significant jump was recorded in 2023/24 with remittances totaling Rs. 1,445.3 billion. Although the figure for mid-June 2023/24 dipped slightly to Rs. 1,327.5 billion, the remittance inflow surged again to a record-high Rs. 1,532.9 billion by mid-June 2024/25. This steady growth reflects increased labor migration, improved remittance channels, and rising global demand for Nepali workers.Sandeep Chaudhary·8 Jul, 2025