Nepal’s Stock Market
Paradigm Shift in Nepal’s Stock Market: SEBON Ties Broker Services to Capital and Risk Capacity
Acknowledging the sheer magnitude of these reforms, SEBON has wisely opted for a staggered, three-phase implementation roadmap. The initial phase will concentrate on laying the groundwork—enforcing broker categorization, capital adequacy, and strict asset segregation. Once the foundation is secure, the second phase will unlock advanced trading tools like intraday trading and short selling, culminating in the third phase focused on advanced supervisory systems and strategic investments. Ultimately, this policy is not merely a set of new rules; it is a calculated, structural blueprint designed to transition Nepal’s stock market into a mature, resilient, and investor-friendly financial hub.
Dipesh Ghimire
3 min read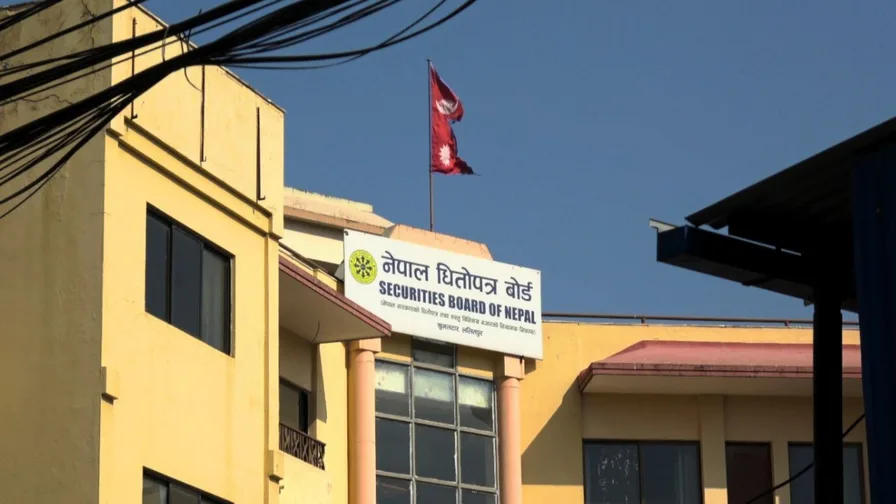
Kathmandu: In what can be described as a watershed moment for Nepal’s capital market, the Securities Board of Nepal (SEBON) has unveiled a transformative policy aimed at overhauling the traditional stock brokerage industry. Moving away from the conventional "one-size-fits-all" approach, the newly approved ‘Securities Brokerage Business Strengthening Policy, 2083’ introduces a merit-based, multi-tier ecosystem. This structural reform is designed to evolve domestic brokers from mere order-executing middlemen into specialized, globally competitive financial institutions, dictating that a broker’s operational scope will now depend heavily on their institutional strength rather than just their license.
The cornerstone of this sweeping reform is the strategic categorization of brokerage firms into four distinct classes: A, B, C, and D. Tier 'A' entities will operate as comprehensive stock dealers, authorized to execute complex, high-yield financial instruments including margin lending, intraday trading, short selling, underwriting, and market making. Tier 'B' will function as full-service brokers with access to advanced trading options, albeit slightly more restricted than dealers. Conversely, Tier 'C' firms will remain confined to traditional client order executions, requiring special regulatory clearance to step out of their basic mandate. Finally, Tier 'D' is reserved for highly specialized niche operations, such as institutional and debenture brokerage. This stratification ensures that retail investors have access to advanced trading tools only through firms that have the actual capacity to handle them.
Perhaps the most critical interpretation of this policy lies in its approach to financial safeguarding. The regulatory board has astutely recognized that introducing advanced trading mechanisms like short selling and margin financing inherently amplifies systemic market risk. Consequently, the era of a static paid-up capital requirement is effectively over. SEBON is pivoting toward a dynamic 'risk-based regulatory capital' model. Firms venturing into high-stakes financial activities will now be legally bound to maintain substantial liquidity buffers and additional capital reserves proportional to their market exposure. To enforce this, SEBON has readied strict punitive measures; failure to maintain the prescribed capital adequacy will trigger immediate regulatory interventions, including dividend freezes and mandatory capital restoration plans.
For the everyday retail investor, the most reassuring aspect of this policy is the aggressive stance on asset protection and technological security. Historically, the Nepali share market has been shadowed by grievances regarding the misappropriation of investor funds by brokerage firms. Addressing this trust deficit directly, the new guidelines mandate absolute segregation of client funds and securities from a broker’s corporate assets. In the event of a broker facing insolvency, a proposed 'Investor Protection and Compensation Fund' will act as a critical safety net. Technologically, the introduction of an 'Emergency Kill Switch'—a mechanism to instantly halt trading during severe cyber-attacks or systemic glitches—alongside mandatory Multi-Factor Authentication (MFA), reflects a proactive approach to modern cyber threats.
Furthermore, the policy strikes a heavy blow to poor corporate governance and hidden monopolies. The renewal of brokerage licenses will no longer be a bureaucratic rubber stamp. Moving forward, renewals will hinge on rigorous audits of a firm's financial health, technology infrastructure, and client grievance redressal history. By forcing the disclosure of 'Beneficial Owners,' SEBON aims to dismantle opaque cross-ownership networks and prevent excessive market control by isolated interest groups. Simultaneously, the policy gently nudges financially weaker brokers toward industry consolidation through mergers and acquisitions.
Acknowledging the sheer magnitude of these reforms, SEBON has wisely opted for a staggered, three-phase implementation roadmap. The initial phase will concentrate on laying the groundwork—enforcing broker categorization, capital adequacy, and strict asset segregation. Once the foundation is secure, the second phase will unlock advanced trading tools like intraday trading and short selling, culminating in the third phase focused on advanced supervisory systems and strategic investments. Ultimately, this policy is not merely a set of new rules; it is a calculated, structural blueprint designed to transition Nepal’s stock market into a mature, resilient, and investor-friendly financial hub.
Advertisement
Written by
Dipesh Ghimire