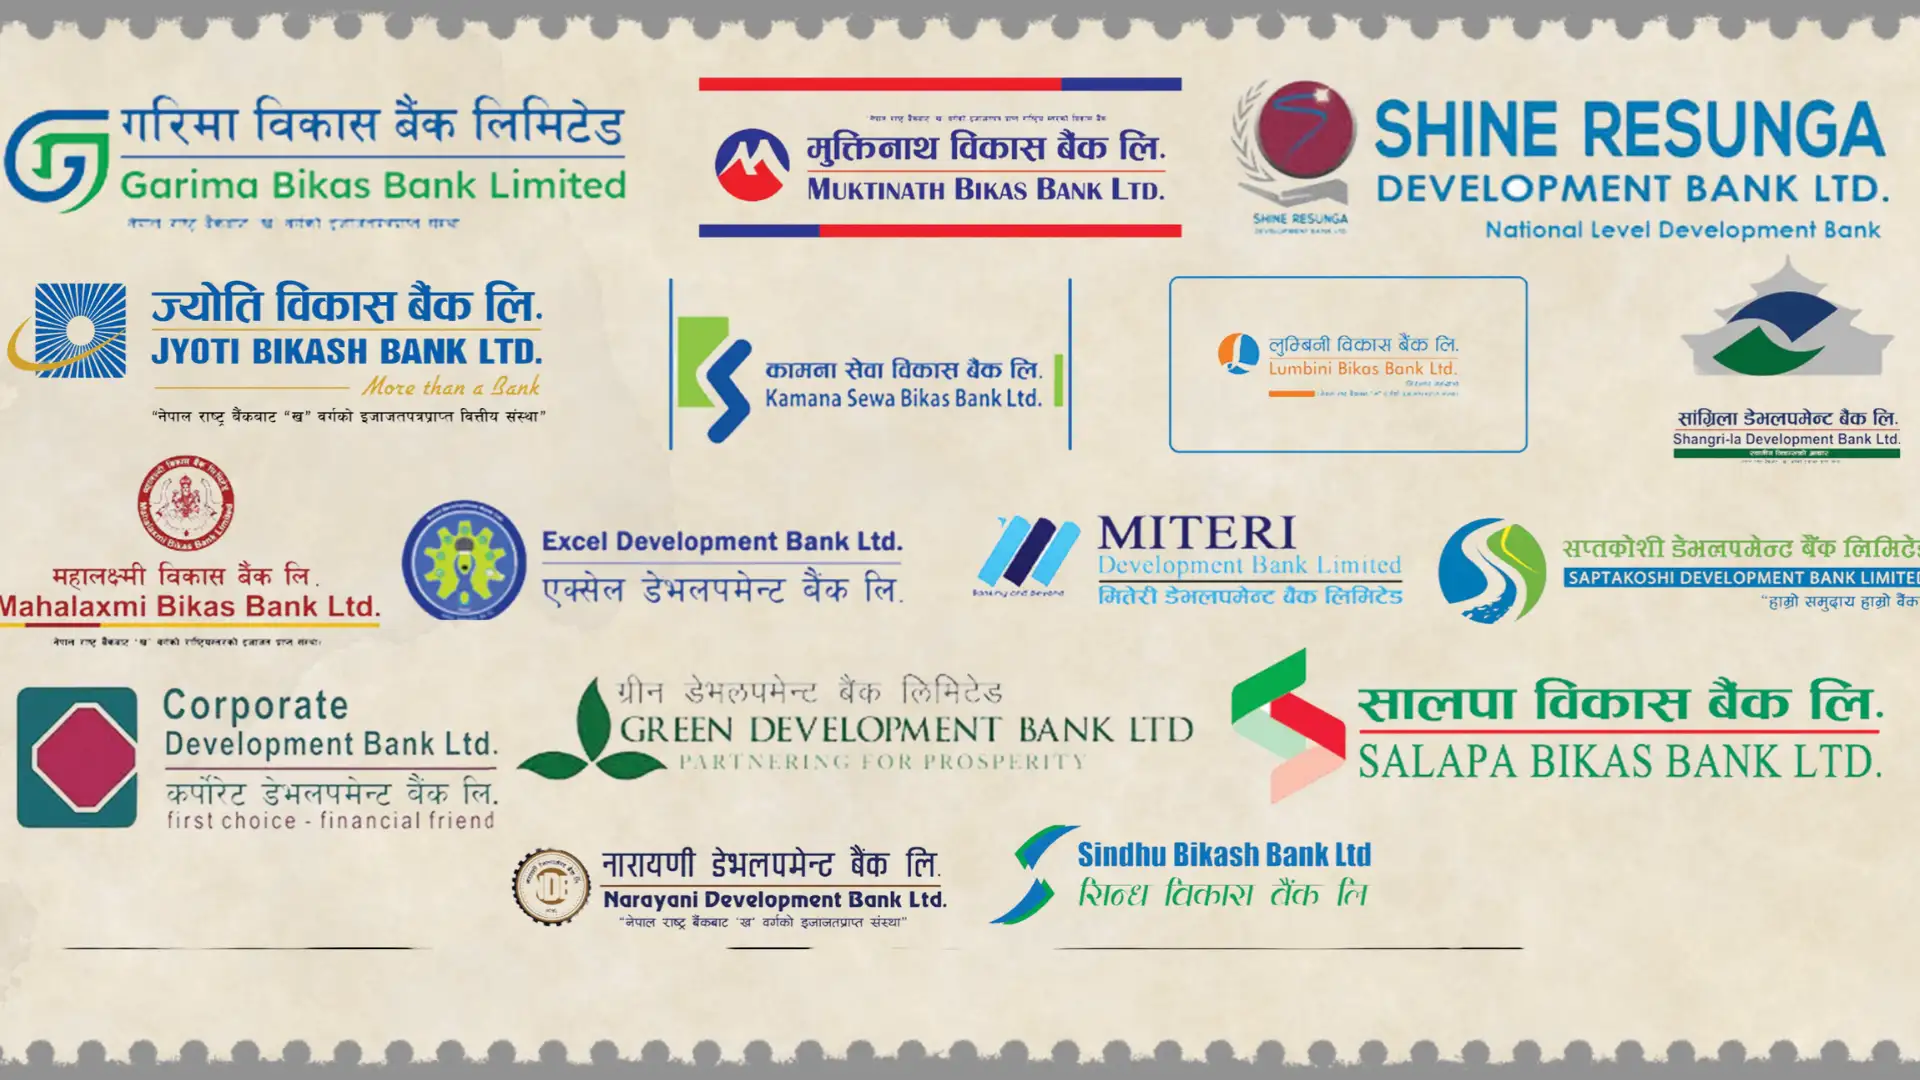
काठमाडौँ — राष्ट्रियस्तरका विकास बैंकहरूले मंसिर महिनाका लागि व्यक्तिगत मुद्दती निक्षेपको नयाँ ब्याजदर सार्वजनिक गरेका छन्। आठवटै विकास बैंकले सार्वजनिक गरेको विवरणअनुसार निक्षेपको अधिकतम ब्याजदर ४.०६ प्रतिशतदेखि ४.५० प्रतिशतको साँघुरो दायराभित्र सीमित देखिएको छ। समग्रमा यी बैंकहरूको व्यक्तिगत मुद्दती निक्षेपको औसत ब्याजदर ४.१८८८ प्रतिशत कायम भएको छ।
बैंकहरूले सार्वजनिक गरेको ब्याजदर तालिकालाई विश्लेषण गर्दा निक्षेप संकलनका लागि बैंकहरूबीच आक्रामक प्रतिस्पर्धा नरहेको स्पष्ट देखिन्छ। अधिकतम र न्यूनतम ब्याजदरबीच निकै झिनो अन्तर रहनुले बैंकिङ प्रणालीमा लगानीयोग्य रकम (तरलता) सहज अवस्थामा रहेको र कर्जाको माग अपेक्षित रूपमा नबढ्दा बैंकहरू महँगो ब्याजमा निक्षेप तान्ने पक्षमा नरहेको संकेत गर्छ। विशेषगरी कुल आठमध्ये पाँचवटा विकास बैंकको ब्याजदर समग्र औसत (४.१८८८ प्रतिशत) भन्दा पनि तल रहनुले ब्याजदर अझै तल्लो विन्दुमै स्थिर रहेको पुष्टि गर्छ।
ब्याजदरसँगै निक्षेपको अवधिलाई हेर्दा आठवटै विकास बैंकले दीर्घकालीन निक्षेपलाई मात्र उच्च ब्याजदरको सूचीमा राखेका छन्। सबै बैंकले कम्तीमा ५ वर्ष वा सोभन्दा बढी अवधिको व्यक्तिगत मुद्दती निक्षेपमा मात्र आफ्नो अधिकतम ब्याजदर प्रस्ताव गरेका हुन्। यसको अर्थ छोटो अवधिको मुद्दती निक्षेप राख्ने ग्राहकले उल्लिखित अधिकतम दरभन्दा अझ कम ब्याज पाउनेछन्। दीर्घकालीन स्रोत सुनिश्चित गर्न बैंकहरूले ५ वर्षमाथिको अवधिलाई प्राथमिकता दिएको तथ्यांकले देखाउँछ।
बैंकगत विवरणअनुसार लुम्बिनी विकास बैंकले ५ वर्षभन्दा बढी अवधिको व्यक्तिगत मुद्दती निक्षेपमा सबैभन्दा आकर्षक अर्थात् ४.५० प्रतिशत ब्याजदर तोकेको छ। लुम्बिनीपछि महालक्ष्मी विकास बैंकले ५ वर्ष वा सोभन्दा बढी अवधिका लागि ४.३० प्रतिशत र सांग्रिला डेभलपमेन्ट बैंकले ५ वर्षभन्दा बढी अवधिका लागि ४.२८ प्रतिशत ब्याजदर निर्धारण गरेका छन्। राष्ट्रियस्तरका आठ विकास बैंकमध्ये यी तीनवटा बैंकले मात्र औसतभन्दा माथिल्लो दरमा ब्याज दिने घोषणा गरेका हुन्।
यता, शाइन रेसुङ्गा डेभलपमेन्ट बैंकले ५ वर्ष वा सोभन्दा बढी अवधिका लागि ४.१५ प्रतिशत र मुक्तिनाथ विकास बैंकले ५ देखि १० वर्षसम्मको अवधिका लागि ४.१० प्रतिशत ब्याजदर कायम गरेका छन्। बाँकी तीनवटा बैंकहरू गरिमा विकास बैंक, ज्योति विकास बैंक र कामना सेवा विकास बैंकले समान रूपमा ५ वर्ष वा सोभन्दा बढी अवधिको निक्षेपमा सबैभन्दा कम ४.०६ प्रतिशत ब्याजदर तोकेका छन्। तीनवटै बैंक एउटै न्यूनतम विन्दुमा अडिनुले बजारको आधारभूत ब्याजदर ४ प्रतिशतको मनोवैज्ञानिक सीमाकै आसपास रहेको देखाउँछ।
विकास बैंकहरूको यो ब्याजदर नीतिले आम निक्षेपकर्ता र ऋणी दुवैलाई प्रत्यक्ष प्रभाव पार्ने देखिन्छ। दैनिक जीवनयापनको लागतको तुलनामा ४ प्रतिशतको हाराहारीमा पाइने ब्याजदरले मुद्दती निक्षेपमै निर्भर रहने बचतकर्ताको वास्तविक प्रतिफल खुम्च्याएको छ। यद्यपि, निक्षेपको लागत सस्तो हुँदै जाँदा बैंकहरूको आधार दर घट्न गई आगामी दिनमा कर्जाको ब्याजदरसमेत थप सस्तो हुने भएकाले उद्योगी, व्यवसायी तथा ऋणीहरूका लागि भने यो अवस्था अनुकूल बन्दै गएको छ।
KATHMANDU — National-level development banks have unveiled their new interest rates on individual fixed deposits for the month of Mangsir. According to the rate schedules published by all eight institutions, maximum deposit rates remain confined within a narrow band of 4.06 percent to 4.50 percent. Overall, the average interest rate on individual fixed deposits across these banks stands at 4.1888 percent.
An analysis of the published rate structures reveals an absence of aggressive competition among development banks to attract deposits. The razor-thin margin between the highest and lowest rates signals comfortable liquidity in the banking system and subdued credit demand, leaving banks with little incentive to mobilize expensive funds. Notably, five out of the eight banks have set their rates below the sector average of 4.1888 percent, confirming that deposit rates remain anchored at lower levels.
Examining deposit tenures alongside interest rates shows that all eight development banks have reserved their peak rates exclusively for long-term deposits. Every institution requires a maturity period of at least five years or more to qualify for its maximum advertised rate. Consequently, customers opting for shorter-term fixed deposits will earn even lower returns, with the data indicating a clear strategic focus by banks on locking in long-term funding sources.
In the bank-by-bank breakdown, Lumbini Bikas Bank leads the pack by offering 4.50 percent on individual fixed deposits with tenures exceeding five years. It is followed by Mahalaxmi Bikas Bank at 4.30 percent for tenures of five years or more, and Shangrila Development Bank at 4.28 percent for deposits above five years. Out of the eight national-level development banks, only these three have positioned their rates above the industry average.
Meanwhile, Shine Resunga Development Bank has fixed its rate at 4.15 percent for five years or above, while Muktinath Bikas Bank is offering 4.10 percent for tenures ranging from five to ten years. The remaining three institutions—Garima Bikas Bank, Jyoti Bikas Bank, and Kamana Sewa Bikas Bank—have all settled at the lowest rate of 4.06 percent for tenures of five years or more. The convergence of three major banks at the exact same floor indicates that the market's baseline rate is hovering right around the psychological 4 percent threshold.
This interest rate trajectory carries direct implications for both savers and borrowers. Against the backdrop of everyday living costs, yields hovering around 4 percent squeeze real returns for depositors who rely on fixed-income savings. Conversely, lower deposit mobilization costs will pull down banks' base rates, paving the way for cheaper lending rates in the coming days—a favorable shift for industrialists, entrepreneurs, and general borrowers.